Why Gold Prices in India Didn't Spike During the War
Why Indians reach for gold when money is tight, why that choice is more rational than it looks, and the one thing about it nobody likes to mention.
Alok Parmar
June 09, 2026
Article Index
Most financial advice tells you to build an emergency fund: three to six months of expenses, kept somewhere safe and accessible. It's good advice. It's also advice that millions of Indian families have been quietly following for generations by keeping gold — without ever calling it an emergency fund. The bangles set aside after a wedding, the coins bought every Akshaya Tritiya, the chain inherited from a grandmother. Nobody labels it that way. But gold as an emergency fund is exactly what it becomes when the family needs it most.
Strip away the sentiment and gold has four properties that, combined, no other household asset matches.
It needs no one's permission. This is the one that matters most. To break a fixed deposit early, you need the bank. To get a loan, you need a lender to approve you. To redeem an investment, you need markets open and a settlement period to pass. Gold needs none of that. The decision to convert it to cash is entirely yours, and it can happen the same day.
There's always a buyer. Gold is liquid in a way few household assets are. It doesn't matter whether the stock market is up or down, whether it's a weekend, or whether your bank is having a system outage. Gold has a market every single day.
Its value doesn't depend on any one institution. A bank can fail. A company's shares can collapse. Gold's value sits outside any single institution's health, which is exactly why people trust it during the moments when institutions feel shaky.
It's already in the house. An emergency asset is only useful if you can reach it in an emergency. Gold doesn't require you to log in, locate paperwork, or wait for office hours. It's physically present, already yours, ready when you are. Put those four together and the picture is clear. When something goes wrong and you need money quickly, gold is the asset that responds fastest and asks the least of you.
1
Gold vs. the Other Options in a Real Emergency
When cash is needed urgently, every option gets judged on two things: how fast it delivers, and how certain that delivery is. Here's how gold compares.
Fixed deposits: Reliable, but breaking one early usually means a penalty, and you're dependent on the bank's process and timing. Not instant.
Mutual funds and stocks: Redemption takes a few working days to reach your account, and the market may be down exactly when you need the money. Speed and certainty both wobble.
Borrowing or a personal loan: Needs a lender to approve you, which takes time and isn't guaranteed. In a genuine emergency, “maybe, after we review your application” isn't useful.
Credit cards: Fast, but capped by your limit and expensive if you can't clear the balance quickly. A short bridge, not a real reserve. Gold sits apart from all of these. It's already in your possession, it can be converted the same day, and nobody has to approve it. That combination of speed and certainty is the whole reason it has survived as the household's fallback.
Here's the honest catch, and it's worth stating plainly even though we buy gold for a living: gold only works as an emergency asset if you can convert it fairly. And an emergency is exactly the moment people are most likely to be short-changed.
The reason is uncomfortable but simple. When you're selling under pressure, that pressure is often visible. A buyer who senses you need cash today, and have no time to compare quotes, has every incentive to offer less — through a rate that's quietly below the live market, through deductions that aren't fully explained, or through a fast verbal calculation you can't easily check. Distress, unfortunately, attracts exploitation. This is the thing to protect yourself against, and you can. A fair transaction has a few non-negotiables: the buyer shows you the live gold rate (IBJA or MCX) before any calculation, tests purity in front of you, and gives you a written breakdown — gross weight, deductions for any non-gold components, net gold weight, purity percentage, the rate used, and the final figure. Every step should be visible. If any of it is hidden or rushed, that's the signal to slow down or walk away. It's also why you shouldn't wait for the emergency to understand your gold. Knowing roughly what your pieces are worth, and what a fair process looks like, before you ever need the money means you're not learning it under pressure — which is precisely when you're most likely to accept a bad deal.
3
Sell It, or Borrow Against It?
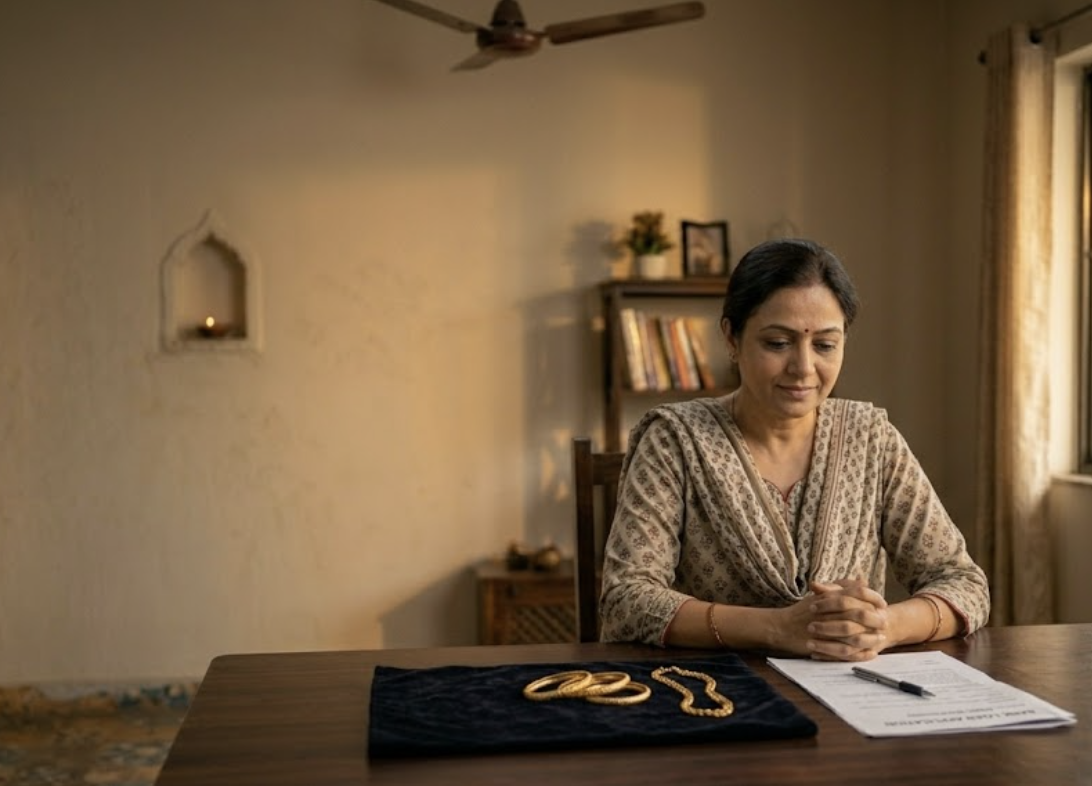
Tapping your gold doesn't always mean selling it. A gold loan lets you borrow against it and get the pieces back later. Which one makes sense depends on your situation.
A gold loan can work when the need is short-term, you have a clear and reliable way to repay (an incoming payment, a stable income), and the pieces carry sentimental value you'd rather not part with. You get cash now and keep the gold, as long as you repay on schedule.
Selling often makes more sense when repayment is uncertain, the expense is ongoing rather than one-time, or you simply want to be free of debt. A one-time conversion can cost less than carrying months of loan interest, and it removes the risk of losing the gold to a default. Neither is automatically right. The point is that you have a choice, and it's worth thinking it through before deciding rather than defaulting to whichever option is in front of you.
What You Can Actually Control: Using your emergency gold can feel like a failure — like you've had to give up something your parents gave you, or set aside for a child's future. That feeling is real, but worth reframing. This reserve existed for exactly this reason. Using it when you genuinely need to isn't losing it. It's the reserve doing the one job it was always there to do.You can't control whether an emergency arrives. You can't control the gold rate on the day you need it. What you can control is whether the conversion is fair — and that's mostly a matter of knowing what your gold is worth and what an honest process looks like, before you're under pressure to decide.If you'd like to know what your gold is genuinely worth — with a full transparent breakdown and no obligation to sell — AsliValue's doorstep evaluation is free. Knowing the number before you ever need it is the simplest way to make sure your safety net actually holds when you reach for it.
Gold Loan vs Selling Gold: What Actually Makes More Sense?
If you're weighing whether to sell your gold or take a loan against it during a financial crunch, the answer depends on a few factors most people don't think to check until they're already in the decision. This breaks it down simply.
aslivalue.com
Find out what your gold is worth before you ever need to
Knowing the number in advance is the simplest way to make sure your safety net actually holds when you reach for it. Our expert comes to your home, tests your gold in front of you and gives you a full written breakdown at the live domestic gold rate. No obligation to sell. Ever.